Last verified: October 2026. This article covers the United States only. Consumer protections come from the CFPB, CMS and the IRS pages listed in the sources, and state laws can add more.
You can often lower a medical bill, but the order matters. Check that you owe it, check that it is correct, find out which legal protections apply, ask about financial assistance, and only then negotiate what remains. The Consumer Financial Protection Bureau (CFPB) puts it simply: make sure the provider accurately calculated the bill and that you owe it before you pay.
This guide is about US medical billing only. Healthcare funding works differently in the UK, EU and Australia.
Key takeaways
- Do not pay immediately. Ask for an itemized bill and compare it with your insurer’s explanation of benefits (EOB).
- The No Surprises Act protects insured people from some out-of-network bills, such as emergency room visits, and gives self-pay patients a right to a good faith estimate.
- Many hospitals must offer financial assistance (“charity care”). Ask for the policy and the application in writing.
- If you still owe money, ask for a lower amount or an interest-free payment plan before you consider a credit card or medical credit card.
- Keep records of every call: date, name and what was agreed. Get any deal confirmed in writing before you pay.
Step 1: Confirm you owe the bill
The CFPB suggests first checking whether you have already paid, and whether the bill might belong to someone else with a similar name. Then ask the billing office for an itemized list of charges and look at it carefully. The CFPB lists these questions:
- Are the charges accurate and do they match the services you received?
- If you have insurance, do the bills reflect your insurer’s payment and what the provider understood would be covered?
- Does any charge say “out-of-network” when it was not?
- Is any service charged twice?
Contact the billing office quickly, because late fees and interest can add up while you wait. The phone number is on the statement.
Step 2: Compare the bill with your EOB
If you have insurance, your insurer sends an explanation of benefits after a claim. It is not a bill, but it shows what the plan allowed and paid and what you may owe. If the provider’s bill is higher than the EOB says you owe, ask the provider to explain the difference. If your plan denied a claim, you have the right to an internal appeal with the insurer and an external review by an independent party. Check your policy documents, and see the HealthCare.gov page on appeals for the process.
| Step | What to do | Look for |
|---|---|---|
| 1. Itemize | Ask the billing office for an itemized list | Duplicates, services you did not get |
| 2. Compare | Match the bill to your insurer’s EOB | Amounts that differ from what you owe |
| 3. Check rights | See if the No Surprises Act applies | Wrongly billed out-of-network care |
| 4. Ask for aid | Request the financial assistance policy | Free or discounted care |
| 5. Negotiate | Ask for a lower amount or interest-free plan | Agreement confirmed in writing |
Step 3: Check which legal protections apply
| Situation | Protection | Where to turn |
|---|---|---|
| Insured, out-of-network emergency care | No Surprises Act | CMS: 1-800-985-3059 |
| No insurance, care scheduled 3+ days ahead | Good faith estimate; dispute if $400+ over | CMS: 1-800-985-3059 |
| Care at a tax-exempt hospital | Financial assistance policy | Hospital billing office |
| Collections or credit report problem | Dispute rights; CFPB complaint | CFPB: (855) 411-2372 |
If you have insurance: the No Surprises Act
The No Surprises Act took effect on January 1, 2022. According to CMS, it applies to most types of health insurance and protects you from unexpected out-of-network bills for:
- emergency room visits,
- non-emergency care related to a visit to an in-network hospital, hospital outpatient department or ambulatory surgical center, and
- air ambulance services.
The CFPB notes that some services, such as ground ambulance transportation, are not protected by the Act. If you think a facility, provider or insurer is not following the rules, you can submit a complaint to CMS at 1-800-985-3059.
If you do not use insurance: the good faith estimate
CMS says that providers must usually give you a good faith estimate of your costs if you ask for one or schedule care at least 3 business days in advance. You may be able to dispute the bill if it is at least $400 more than the estimate.
Hospital financial assistance
A hospital that is tax-exempt under Section 501(c)(3) has to meet extra requirements under Section 501(r) of the tax code. The IRS says these include a written financial assistance policy (FAP) that sets the eligibility criteria, whether assistance means free or discounted care, how to apply, and the basis for the amounts charged. Once someone is found eligible under the FAP, they may not be charged more than the “amounts generally billed” for emergency or medically necessary care.
In practice:
- Ask the hospital billing department for its financial assistance policy, the application and a plain-language summary. The IRS says hospitals must make these widely available, including on a website.
- Check which providers the policy covers. The FAP must include a list of the providers delivering care in the hospital that specifies which are and are not covered by it.
- Apply before the bill goes to collections where you can. The IRS notes that financial assistance may not be denied for missing documentation that the policy did not require.
Some states have charity care laws that go further. The CFPB also notes that older adults enrolled in the Qualified Medicare Beneficiary program should not be billed for Medicare-covered cost sharing, and that veterans may qualify for help from the VA.
Step 4: Negotiate what is left
After errors, insurance and financial assistance are sorted out, the CFPB’s options for what you still owe are to negotiate the bill down to an amount you can afford, ask for an interest-free repayment plan, or look for nonprofit help with medical costs.
What to say
- “Can you tell me the lowest amount you would accept to settle this account?”
- “If I pay in full today, is there a discount?”
- “Can I set up a payment plan with no interest?”
There is no guaranteed discount, and what is offered varies by provider. A calm, specific request with documents in hand is more likely to get a useful answer than a general complaint. Always get the agreement in writing, including the amount, due date and a statement that the account will be marked paid or settled, before you send money.
How to prepare for the call
- Have the itemized bill, the EOB and your account number in front of you, and note the date and time of every call.
- Write down the specific charges you are questioning and what you want: removal, a lower total, or a payment plan.
- Ask to speak with someone in the billing or financial assistance department if the first person cannot change the account.
- Ask whether the account can be put on hold while a dispute or financial assistance application is under review, and get any such hold confirmed in writing.
- Follow up in writing, by letter or the provider’s patient portal, so there is a record of what was agreed.
Be careful with credit cards and medical credit cards
The CFPB warns that paying with a credit card or medical credit card can mean high interest, and that you may lose the ability to negotiate the debt. An interest-free repayment plan with the provider may be better. See our buy now, pay later guide for how deferred-interest and instalment products work.
What if the bill goes to collections?
If a bill is sent to a debt collector, the CFPB says you can still dispute it with the collector or with a credit reporting company. Do not assume the collector is correct; confirm that you owe the amount first. The CFPB debt collection page explains your rights.
Medical bills and your credit report
The three national credit bureaus announced voluntary changes: paid medical collections have been removed from reports since July 1, 2022, the wait before unpaid medical collections appear was extended from six months to one year, and medical collections with an initial balance under $500 were removed from April 11, 2023. These are industry policies and can change. A federal rule that would have banned medical debt from credit reports was vacated by a court on July 11, 2025, so check your reports yourself.
If you have a problem with debt collection or credit reporting because of a surprise medical bill, you can submit a complaint to the CFPB online or by calling (855) 411-2372.
Worked example: a $4,200 hospital bill
This is a hypothetical illustration. Providers set their own policies and nothing here is guaranteed.
Sam receives a $4,200 hospital bill after a procedure.
- Sam asks for an itemized bill and finds a $350 charge duplicated. The provider removes it: $4,200 − $350 = $3,850.
- Sam compares the bill with the EOB, confirms the remaining amount matches what the plan said he owes, and applies for financial assistance. In this illustration he is not eligible.
- Sam asks for a prompt-payment discount and the provider agrees to 20% off: $3,850 × 0.80 = $3,080.
- Because Sam cannot pay at once, he asks for an interest-free plan over 12 months: $3,080 ÷ 12 ≈ $257 a month.
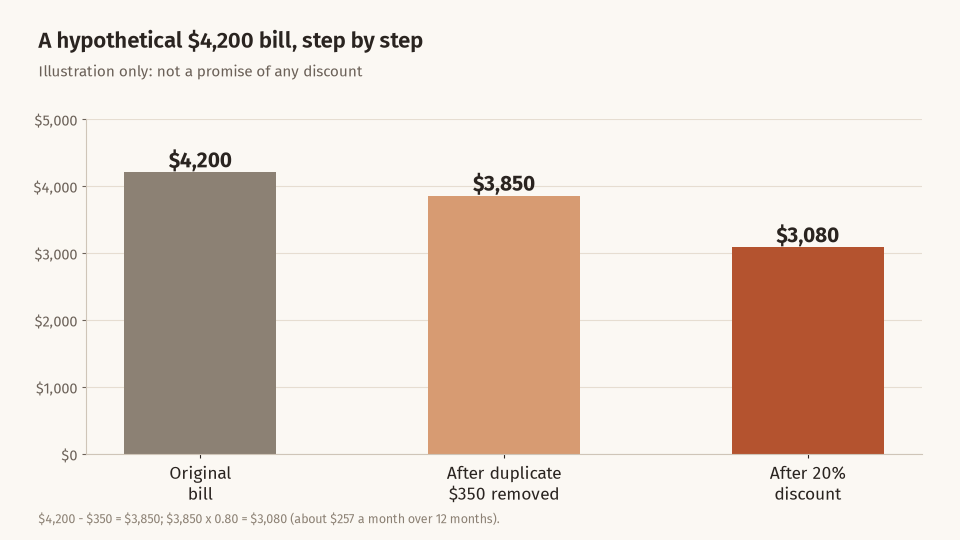
Medical costs and your taxes
If you itemize, the IRS worksheet for 2026 shows that medical and dental expenses can be deducted to the extent they exceed 7.5% of your income. Many households do not reach that threshold, so check before relying on it. Money in an HSA or health FSA can pay qualified medical expenses with pre-tax dollars; see our HSA vs FSA guide. For wider ideas about lowering your bill each year, see how to legally reduce your taxable income.
Common mistakes
- Paying before checking. Pay only once you have confirmed that you owe the amount.
- Ignoring the bill. The CFPB says that doing nothing could mean late fees, interest, collections, lawsuits, garnishments and lower credit scores.
- Not asking for an itemized bill. A summary total hides duplicate and incorrect charges.
- Assuming insurance paid correctly. Compare the bill with your EOB.
- Not asking about financial assistance. It is a written policy at many hospitals, and you generally have to apply.
- Using a credit card by default. You might swap a negotiable debt for interest-bearing one.
- Making a verbal deal only. Get it in writing.
- Assuming ground ambulance bills are covered by the No Surprises Act. They are not.
Frequently asked questions
Can I really negotiate a medical bill?
Yes, you can ask. The CFPB lists negotiating the bill down and asking for an interest-free repayment plan as options. Providers differ in what they will agree to.
What is a good faith estimate?
A cost estimate that providers must usually give self-pay or uninsured patients who request one or schedule care at least 3 business days ahead. You may be able to dispute a bill that is at least $400 higher.
Does medical debt hurt my credit score?
Unpaid medical debt in collections can be reported, although the major credit bureaus announced they exclude paid collections, wait a year before reporting unpaid ones and exclude those under $500. These are voluntary policies, so check your reports.
What if I cannot pay at all?
Ask about financial assistance first, then a payment plan. The CFPB also points to nonprofit organizations that help with medical costs. If you are contacted by a collector, you can dispute the debt.
Who do I complain to?
CMS (1-800-985-3059) handles No Surprises Act complaints. You can complain to the CFPB about debt collection or credit reporting problems at (855) 411-2372, and your state insurance department may also help.
This article is general consumer education about US medical billing, not legal, financial or medical advice. Laws and policies change, and your situation is your own. Check the sources below, and consider contacting your state’s consumer assistance program or a qualified professional. See our Editorial Policy and Disclaimer pages for how we work.
Sources
- CFPB: What should I do if I can’t pay a medical bill?
- CMS: Medical bill rights (No Surprises Act)
- IRS: Financial assistance policy and emergency medical care policy, Section 501(r)(4)
- HealthCare.gov: Appealing a health plan decision
- CFPB: Debt collection resources
- CFPB: Medical debt credit reporting rule (Regulation V) status
- Equifax, Experian and TransUnion press release (April 11, 2023)
- IRS: 2026 Form W-4