Last verified: October 2026. Figures and rules below were checked against the official sources listed at the end of the article.
Debt consolidation means replacing several debts with one new loan, so you make a single payment to a single lender. It helps when the new loan lowers your total cost, has a clear end date, and you stop adding new debt. It backfires when the lower monthly payment simply comes from stretching the debt over more years, or when you run the old cards back up. The question to ask is not “is my payment smaller?” but “will I pay less in total, and can I stay out of new debt?”
This guide explains how consolidation works, the main ways to do it, how to check the real cost with a worked example, and what to try first.
Key takeaways
- Consolidation does not erase debt. It moves it into a new loan, and the new loan has its own rate, fees and term.
- Compare total cost, not just the monthly payment. The CFPB warns a lower payment may come from a longer term that costs more overall.
- It only works if the cause of the debt is fixed. The CFPB says that if you spend more than you earn, a consolidation loan probably will not help unless you cut spending or raise income.
- Secured loans put your home or car at risk. Moneysmart and MoneyHelper both say to consider other options first.
- Free help exists. Nonprofit credit counselors (US), MoneyHelper-listed debt advisers (UK) and the National Debt Helpline (Australia) can help before you borrow.
What debt consolidation is
Moneysmart defines consolidation as rolling several debts into one new loan, so you then make one regular repayment to one lender. You can consolidate credit cards, personal loans, store cards, buy now pay later and car loans. Refinancing, which replaces or extends an existing loan with a new one, can be used as part of consolidation.
The attraction is simplicity: one payment, one date. The risk is that simpler is not the same as cheaper.
Ways to consolidate
| Option | How it works | Main catch |
|---|---|---|
| Balance transfer card | Move card debt to a 0% or low-rate card | Promotional rate ends; transfer fee |
| Personal loan | One new loan pays off the old debts | Lower payment may just mean a longer term |
| Home equity or secured loan | Borrow against your home or another asset | You could lose the asset if you cannot pay |
| Debt management plan | A debt adviser arranges repayments with creditors | Not a new loan; check who runs it and any fees |
Balance transfer credit card
The CFPB says many card companies offer zero or low-interest balance transfers to bring card debt onto one card. The catches:
- The promotional rate lasts for a limited time. After that, the rate may rise.
- You will probably pay a balance transfer fee, usually a percentage of the amount or a fixed amount, whichever is more.
- If you use the card for new purchases, you lose the grace period and pay interest until the whole balance, including the transferred amount, is paid off.
- If you are more than 60 days late, the card company can raise the rate on all balances, including the transferred one.
MoneyHelper says a 0% or low-interest balance transfer card can be the cheapest option, as long as you repay within the promotional period, and notes you will probably need a good credit score.
Personal (consolidation) loan
The CFPB says banks, credit unions and installment lenders may offer loans that convert many debts into one payment. Some low rates may be teaser rates that rise later. A lower monthly payment may come from paying over a longer time, which can mean paying a lot more overall, including fees you would not otherwise have paid. MoneyHelper adds that unsecured loans usually need a good credit score for the best deals.
Home equity or other secured loans
Borrowing against your home may carry a lower rate, but the CFPB calls using a home equity loan to consolidate card debt risky: if you do not repay it, you could lose your home. You may also pay closing costs, and falling house prices could leave you “underwater”. MoneyHelper says missing repayments on a secured homeowner loan could cost you your home. Moneysmart says to consider all other options before using your home or other assets as security.
A debt management plan or help from a counselor
MoneyHelper says a debt adviser might negotiate with your creditors and arrange a repayment plan, or a Debt Management Plan. The CFPB recommends free support from a nonprofit credit counselor. In Australia, Moneysmart points to free financial counsellors through the National Debt Helpline.
A worked example: three debts, one loan
This is an illustration with made-up numbers. Suppose you owe $15,000 across three debts:
| Debt | Balance | Interest rate | Monthly payment to clear in 3 years | Interest paid |
|---|---|---|---|---|
| Card A | $6,000 | 24% | $235 | $2,474 |
| Card B | $4,000 | 19% | $147 | $1,278 |
| Loan C | $5,000 | 12% | $166 | $979 |
| Total | $15,000 | $548 | $4,731 |
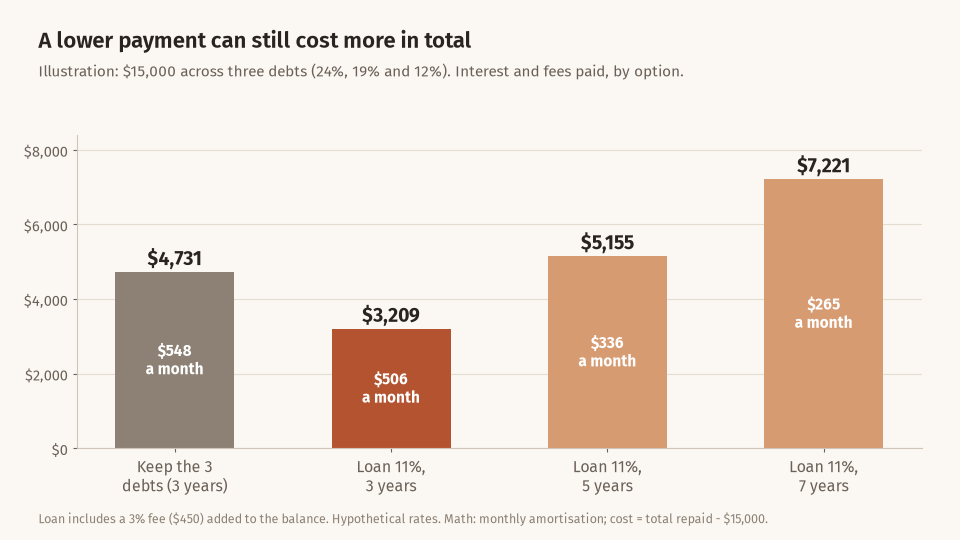
Now suppose you are offered a single loan at 11% with a 3% fee ($450) added to the balance, so you borrow $15,450. Over different terms:
| Option | Monthly payment | Total interest and fees |
|---|---|---|
| Keep the 3 debts (3 years) | $548 | $4,731 |
| New loan, 3 years | $506 | $3,209 |
| New loan, 5 years | $336 | $5,155 |
| New loan, 7 years | $265 | $7,221 |
The three-year loan cuts the total cost by $4,731 − $3,209 = $1,522 and lowers the payment a little. The five-year loan has a much lower payment, but costs $5,155 − $4,731 = $424 more. The seven-year loan costs $2,490 more than just paying off the original debts. The monthly figures assume payments made monthly with interest compounding monthly. Your lender may calculate differently.
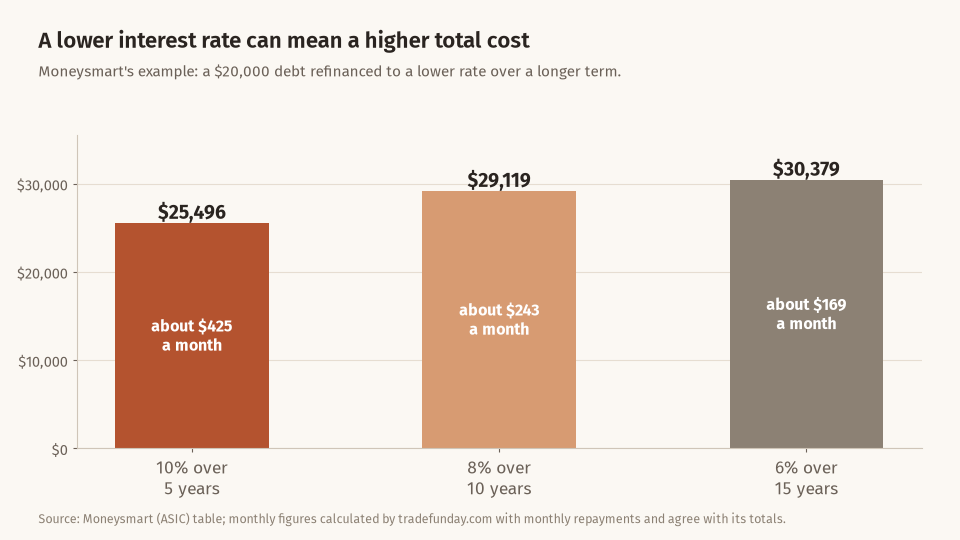
Moneysmart makes the same point with its own example: a $20,000 debt at 10% over five years costs $25,496 in total; at 8% over ten years it costs $29,119; at 6% over fifteen years, $30,379. The rate falls each time, but the total cost keeps rising. We recalculated these with monthly repayments, and they agree.
When consolidation helps
Moneysmart and MoneyHelper give similar tests. Consolidation tends to help when:
- You pay less overall. The interest rate and fees on the new loan are lower than on your current debts, and fees do not wipe out the savings.
- There is a clear end date. The new term is not longer than your current debts.
- You can afford the payments. Moneysmart suggests stress-testing your budget for higher interest rates, lower income and higher living costs.
- You stop using the old credit. Moneysmart says to close or reduce old cards and avoid new debt.
- It clears all your payments. MoneyHelper’s first test is that the loan clears all your outgoing payments.
If you can pay off a promotional balance transfer before the offer ends, it can be the cheapest route, but you must be realistic about whether you can. If your credit has been hurt, the CFPB says you probably will not qualify for the low rates.
When it does not help
- You are still spending more than you earn. The CFPB says a consolidation loan probably won’t get you out of debt unless you reduce spending or increase income, and that taking on new debt to pay old debt may just be “kicking the can down the road”.
- The term is longer. As the example shows, lower payments can mean higher total cost.
- You would have to secure the loan against your home for a rate you could get another way.
- Fees cancel the savings. Moneysmart lists application, legal and valuation fees on secured loans. MoneyHelper mentions early repayment fees on existing loans and fees to arrange the new loan.
- You will go back to the cards. Moneysmart warns that freed-up credit may tempt you to spend more.
Try these first
The CFPB and MoneyHelper both suggest steps before taking a new loan:
- Understand why you are in debt. If spending outpaces income, fix that first. Our budgeting guide shows how.
- Contact your creditors. The CFPB says some creditors may accept lower minimum payments, waive fees, reduce your rate or change your due date.
- Consider savings. MoneyHelper says if you have savings, work out if you would be better off using them to repay early. Keep your emergency fund intact, though.
- Pick a payoff method. Our guide to debt payoff: avalanche vs snowball explains two ways to clear several debts without a new loan.
- Talk to a free adviser. Nonprofit credit counselors in the US, free debt advice in the UK and the National Debt Helpline (1800 007 007) in Australia.
Beware of scams and “too good to be true”
The CFPB warns that many companies advertising consolidation may actually be debt settlement companies, which often charge up-front fees and may convince you to stop paying your debts. Moneysmart says not to trust a company that is not licensed, asks you to sign blank documents, refuses to discuss repayments, rushes the transaction or will not put all costs in writing before you sign. MoneyHelper warns against products that promise to instantly repair your credit score or make you debt free overnight, and against providers that charge upfront fees.
Effect on credit
Consolidation is new borrowing, so how you manage it matters. MoneyHelper says consolidation loans are “another form of lending” and you must keep paying on time. Our guide to how credit scores work explains how late payments and new applications show up on your report, so read it before you apply.
Common mistakes
- Choosing the lowest payment. It usually has the longest term.
- Forgetting the fee. A 3% fee on $15,000 is $450, which in our example was financed and charged interest.
- Not checking the APR. MoneyHelper says to look beyond the advertised rate and compare the APR, or APRC for secured loans.
- Using the balance transfer card for new spending. The CFPB says that removes the grace period on purchases.
- Missing the end of the promotional rate. Set a payoff plan that finishes before it ends.
- Running the cleared cards up again. This is the most common way consolidation makes things worse.
Frequently asked questions
Does debt consolidation hurt my credit?
It involves new borrowing, and your credit may be affected by applications and by how you manage the new loan and the old accounts. Paying on time matters most. MoneyHelper says consolidation is another form of lending, so you need to keep up with payments.
Is a balance transfer better than a consolidation loan?
It can be cheaper if you repay within the promotional period, MoneyHelper says. But the promotional rate ends, there is usually a fee, and new purchases can lose their grace period, according to the CFPB. A loan has a fixed term and payment, which can suit people who need structure.
Should I use my home to consolidate?
Be careful. Secured loans can offer lower rates, but you could lose your home if you cannot pay. Moneysmart and MoneyHelper say to consider other options before putting your home up as security.
What if I cannot afford my payments at all?
Consolidating may not be the answer. Contact your creditors and a free debt adviser first. MoneyHelper says a debt adviser might negotiate with creditors or arrange a repayment plan. In Australia, call the National Debt Helpline on 1800 007 007.
Are debt consolidation companies safe?
Some are legitimate; others are debt settlement companies with up-front fees. The CFPB advises caution, and Moneysmart says to check a company’s licence and get all costs in writing before signing.
How do I compare a consolidation offer with my current debts?
List each debt’s balance, rate, fees and remaining term, then ask the new lender for the rate, all fees, term and repayment. Compare total cost over the full term, as in the worked example above.
This article is general information, not financial advice. Rules, limits and rates change, and your circumstances are your own. Check the official sources below, and consider speaking to a qualified adviser before making decisions. See our Editorial Policy and Disclaimer pages. Last verified: October 2026.
Sources
- CFPB: What do I need to know about consolidating my credit card debt?
- MoneyHelper: Debt consolidation loans
- Moneysmart (ASIC): Debt consolidation and refinancing