Last verified: October 2026. Tax rules and allowances quoted here were checked against the official pages listed at the end of the article, and the worked examples were recalculated.
Passive income is real, but it is rarely effortless or free. It usually comes from money you have already invested (interest, dividends, rent) or from work you did upfront (a book, a course, a product), and the amounts are often small at first. Offers that promise large, guaranteed income for little effort are where regulators see the most harm.
This guide explains what counts as passive income, what it takes to build, what a rental property really leaves you with, how it is taxed in the US, UK and Australia, and which warning signs the FTC and Moneysmart list.
Key takeaways
- “Passive” has a specific meaning for tax. The IRS treats rental activities as passive in general, even if you are hands-on.
- Capital does the work. At an assumed 4% yield, $500 a month needs about $150,000 invested. That is a maths fact, not a forecast.
- Rent is not profit. In our example, $1,800 of rent leaves $56 a month after assumed costs and a manager.
- Income is taxable. The US, UK and Australia all expect dividends and rent to be reported.
- Guaranteed returns are a red flag. The FTC says no one can guarantee that you will make money in business.
What counts as passive income
In everyday use, passive income means money that arrives without you working for it hour by hour. In tax law the term is more specific. The IRS says passive activities include trade or business activities in which you do not materially participate, meaning you are not involved in the operation on a regular, continuous and substantial basis. It adds that, in general, rental activities are passive even if you do take part.
That difference matters because no source is entirely hands-off. Even a savings account needs you to pick it and keep an eye on the rate. A rental needs a tenant, repairs and records. A book or course needs writing and updating. Treat “passive” as meaning “less active”, not “none”.
The realistic sources
Interest, dividends and fund income
You put money in, and it pays you. The IRS says dividends are distributions of earnings and profits paid by a corporation to its shareholders, and that mutual funds, exchange-traded funds, money market funds and real estate investment trusts also pay dividends that pass through to you. If you want to get started, our guide to investing for beginners covers the basics.
The catch is that you need capital first, and the investment itself can fall in value. Dividend and interest payments are also income you must report.
Rental property
Rent can be a steady source, but it is not free money. The IRS says rent is taxable, and that you can generally deduct expenses such as depreciation, repairs and operating costs.
Creating something
Books, courses, apps, templates and videos can earn income after the work is done. This is the area where hype is loudest. The FTC says that promises of guaranteed income, large returns or a “proven system” are likely a scam, and that no one can guarantee that you will make money in a business. A genuine product still needs upfront work, marketing and ongoing support, and many earn little.
If you earn money from side work in the UK, GOV.UK notes a £1,000 trading allowance for casual income. We cover side work in our guide to starting as a freelancer.
What it takes: the capital maths
The simplest passive income is investment income, and the arithmetic is easy. Capital needed equals the income you want per year divided by the yield you assume.
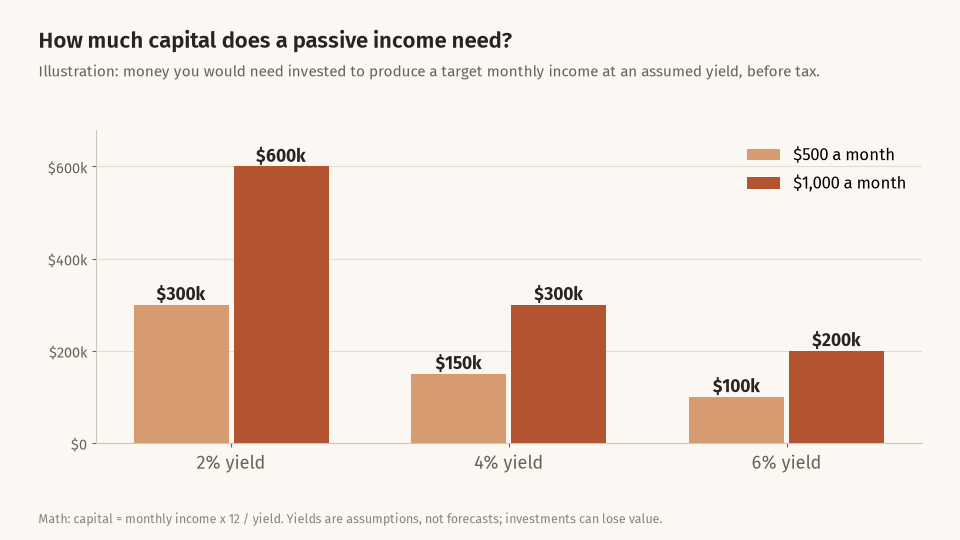
These yields are assumptions to show the math, not forecasts, and real yields change. The point is the scale:
- $500 a month is $6,000 a year. At an assumed 2% yield, that needs $300,000. At 4%, $150,000. At 6%, $100,000.
- $1,000 a month is $12,000 a year. It needs $600,000 at 2%, $300,000 at 4% and $200,000 at 6%.
A higher yield needs less capital, but Moneysmart warns that high returns usually mean a higher risk of losing your money. All of these figures are before tax. Most people build the capital over many years, which is why the emergency fund and ordinary saving come first.
Worked example: a rental property
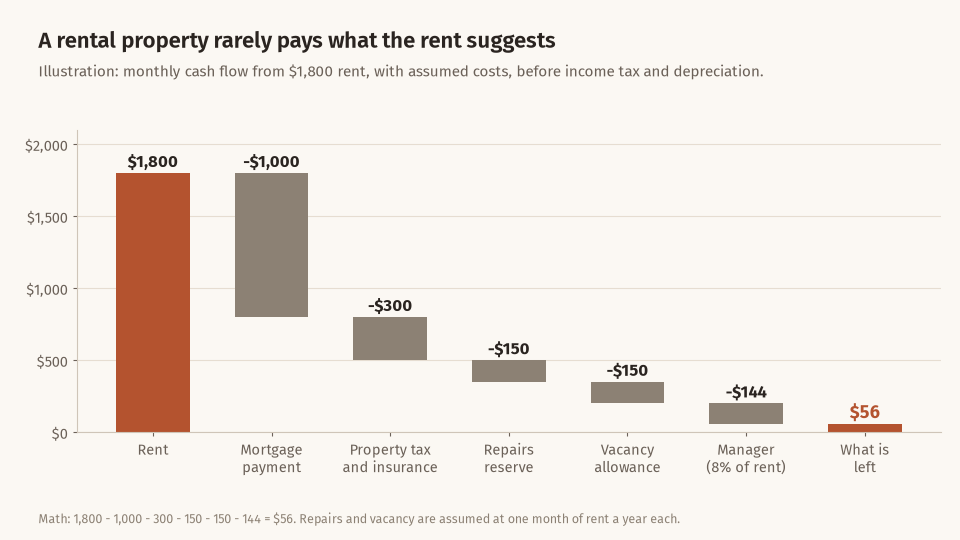
This is an illustration with assumed figures, not a typical property.
- Monthly rent: $1,800
- Mortgage payment: $1,000
- Property tax and insurance: $300
- Repairs reserve: $150 (about one month of rent a year)
- Vacancy allowance: $150 (about one month a year)
$1,800 – $1,000 – $300 – $150 – $150 = $200 a month before income tax. If you hire a manager at an assumed 8% of rent ($144), what is left is $56 a month. The example ignores depreciation, which the IRS lists as a deductible expense, and the tax you may owe on any profit.
That does not mean property is a bad idea. It means you should work out the real net number before relying on it. You also need to consider that a vacant month, a major repair or a rise in the mortgage rate would change the result a lot, and that the property is a large amount of money tied up in one asset.
How passive income is taxed
| Income | United States | United Kingdom | Australia |
|---|---|---|---|
| Dividends | Ordinary or qualified; Form 1099-DIV; report over $1,500 on Schedule B | £500 dividend allowance; none on dividends inside an ISA | Declare in your return; franking credits may apply |
| Rental income | Taxable; usually Schedule E; rentals generally passive for loss rules | £1,000 property allowance; above that, declare it | Declare all rent, in the year the tenant pays; share by ownership |
All three countries expect you to report it.
- United States. The IRS says taxable ordinary dividends over $1,500 go on Schedule B and that dividends can be ordinary or qualified, with qualified dividends taxed at lower capital gain rates. Rental income is generally reported on Schedule E. Passive activity losses that exceed passive income are generally disallowed for the year, but can be carried forward. A rental profit may also be subject to the net investment income tax.
- United Kingdom. For 2026/27, GOV.UK gives a £500 dividend allowance, and dividends above it are taxed at 10.75% (basic rate), 35.75% (higher rate) or 39.35% (additional rate). There is no tax on dividends from shares in an ISA. Separately, there is a £1,000 property allowance and a £1,000 trading allowance each year. If gross property income is over £1,000 up to £2,500 you contact HMRC, and over £2,500 you register for Self Assessment.
- Australia. The ATO says you must declare investment income including interest, dividends and rent. If dividends carry franking credits, you declare both the franked amount and the credit. You must declare the gross rent, in the year the tenant pays it, according to your ownership share.
Tax rules are detailed and change, so confirm the position for your own situation with the official source or a tax professional.
How to spot passive-income hype
The FTC and Moneysmart both list signs. Be cautious if you see:
- Guarantees. The FTC says promises of guaranteed income, large returns or a “proven system” are likely a scam. It also says claims like “You can make 5-6 figures if you follow our system” do not happen.
- Made-up numbers. Its example is “our students make between 50% to 100% return on their investment in the first year”.
- Pressure. The FTC says honest business opportunities do not need high-pressure tactics, and an offer that is good today should be good tomorrow. Moneysmart lists “last chance” and “guaranteed returns” as pressure phrases.
- Testimonials and influencers. The FTC says to read success stories with skepticism, because they might not be true or typical. Moneysmart says celebrities and influencers may be paid to promote investments.
- Upsells. The FTC says if a promoter asks for more money to help your business succeed, stop.
- No clear explanation. Moneysmart says that if you cannot explain how the investment makes money and what the risks are, research more.
The FTC suggests asking: what would I be selling or doing, how would the business make income, what would my expenses be, and when would I expect a profit? It says “turnkey” businesses that are profitable are rare at best. On its job scams page, the FTC says a claim that you can make a lot of money in a short period with little work is almost certainly a scam.
A simple, realistic approach
- Build a base first. Emergency savings and costly debt come before any income project.
- Use accounts that fit your country. For retirement and tax-sheltered investing, see our guide to 401(k) vs IRA, with UK and Australian equivalents.
- Know your net number. Subtract costs, tax and time before you rely on an income stream.
- Start small. Test a side project before paying for a course.
- Think in decades. Moneysmart says most wealth builds over time, not overnight.
Common mistakes
- Paying for a course before testing the idea. Check what the seller actually earns from its customers, as well as what it claims.
- Using gross numbers. Rent, revenue and dividend figures mean little before costs and tax.
- Chasing the highest yield. Higher advertised returns usually come with a higher risk of loss.
- Borrowing to invest in an income stream. Moneysmart’s checklist asks whether you are borrowing to invest and whether you can afford to lose the money.
- Forgetting to report income. All three countries expect it.
- Ignoring the time cost. Passive does not mean zero hours.
- Acting on fear of missing out. Moneysmart asks whether you would still invest if no one else were talking about it.
Frequently asked questions
Is passive income real?
Yes, for example dividends, interest and rent. It usually needs capital or upfront work, and the income can change. Official sources warn against schemes promising guaranteed or large returns for little effort.
How much money do I need for $1,000 a month?
It depends on the yield. At an assumed 2% it is $600,000, at 4% it is $300,000 and at 6% it is $200,000, before tax. These yields are assumptions, not forecasts.
Is rental income passive for tax purposes?
In the US, the IRS says rental activities are generally passive. In the UK and Australia, rent is still income you may need to declare. Rules differ, so check the official source for your country.
Are dividends taxable?
Yes in general. The UK has a £500 dividend allowance for 2026/27 and no tax on dividends inside an ISA. The US distinguishes ordinary and qualified dividends. Australia may attach franking credits.
How do I tell if a passive-income course is a scam?
Look for guarantees, made-up numbers, pressure and upsells. The FTC says promises of guaranteed income or a “proven system” are likely a scam. Search the seller’s name with words like “scam” or “complaint”, and talk to someone you trust before paying.
What should I do first?
Build emergency savings, pay down costly debt and make sure you are using any workplace retirement contributions. Then look at low-cost, diversified investing.
This article is general information, not financial advice. Rules, limits and rates change, and your circumstances are your own. All figures in the worked examples are hypothetical. Check the official sources below, and consider speaking to a qualified adviser before making decisions. See our Editorial Policy and Disclaimer pages. Last verified: October 2026.
Sources
- IRS: Topic no. 425, Passive activities – Losses and credits
- IRS: Topic no. 404, Dividends and other corporate distributions
- IRS: Topic no. 414, Rental income and expenses
- GOV.UK: Check if you have to pay tax on dividends
- GOV.UK: Tax-free allowances on property and trading income
- Australian Taxation Office: Investment income
- Australian Taxation Office: Rental income you must declare
- FTC: When a business offer or coaching program is a scam
- FTC: Job scams (work-from-home section)
- Moneysmart (ASIC): Don’t get burned by investment hype (updated 2 October 2026)